
Want to move? Homeowners in these 6 U.S. cities could see their mortgage payments more than double
The housing market is locked up—and by looking at one key number, it’s easy to see why.
High mortgage rates are the main force freezing existing U.S. homeowners in place, with many would-be home sellers reluctant to part ways with much lower rates from a bygone era. But just how much more would they be paying in today’s real estate ecosystem?
It turns out, the answer is a lot. Today, the average homeowner would pay $1,100 more every month compared with existing mortgage holders for a median-priced home, according to a new report from Realtor.com. High rates, combined with stubbornly high home prices, have created a perfect storm in the market, dissolving the dream of homeownership for some while keeping existing homeowners tethered, even when they’d rather relocate.
“Home sales have been stuck for several years, and this research helps illuminate one of the major friction points for today’s homeowners who might like to move,” Realtor.com chief economist Danielle Hale said in the report. “For the typical mortgage holder, buying a home at today’s median price and current rates would mean finding about $1,100 more each month for principal and interest, before property taxes and insurance.”
On average, the cost of buying a home in the U.S. has risen from $1,332 to $2,468 per month—an 85.3% change. Those numbers are based on a median-priced home with a 14.3% down payment and a 7.32% mortgage rate, typical for the current market, compared with the 4% average rate attached to outstanding mortgages.
Hale notes that lower rates would offer some relief, but because the cost of buying a home today has gone up so much, an incremental drop in rates wouldn’t do the trick. “Even at 6%, the typical payment would still be more than 60% higher,” she said. “For many families, that is money they simply don’t have to spare.”
Monthly costs soar
The average national numbers are painful enough on their own, but in some U.S. cities the situation is even more dramatic, with homeowners extremely locked in to affordable monthly payments and unable or unwilling to move.
In Portland, Maine, the typical current mortgage holder pays $1,270 a month at a 4% interest rate. Buying a new home there today with 21% down costs an average of $3,392 a month—a monthly budget hit of more than $2,000. That 167% percentage increase in monthly mortgage costs under current rates is the highest in the nation, but other cities aren’t far behind.
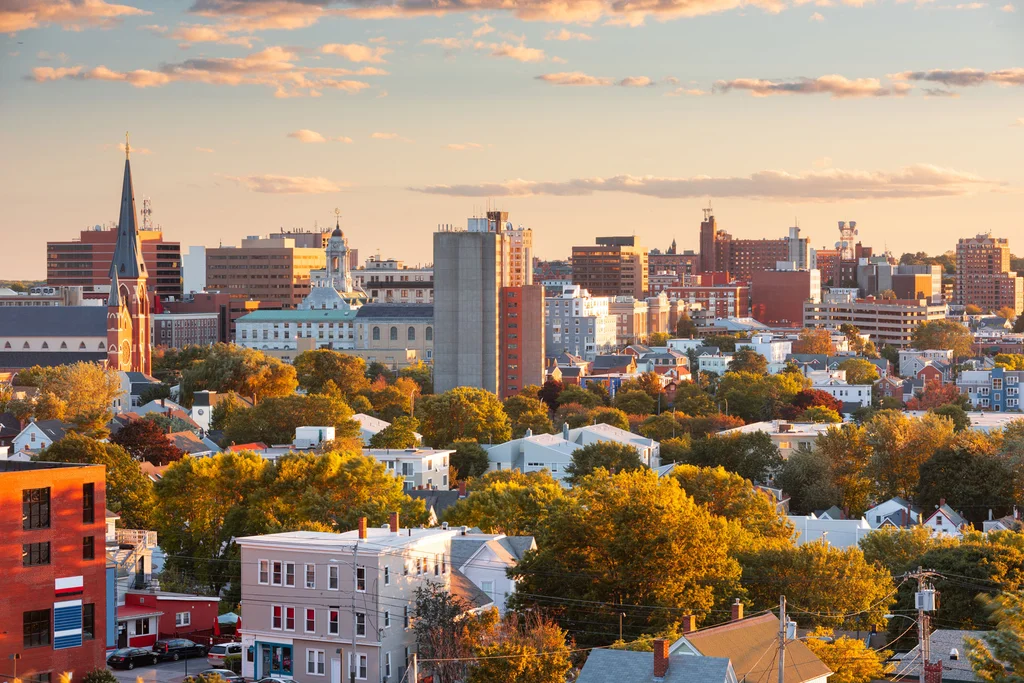
In the greater San Jose area, the cost of a monthly mortgage has ballooned from $2,659 for current mortgage holders to $7,039—a massive 165% increase, even for homeowners with a market-typical 26% down payment. Los Angeles; Albany, New York; Providence, Rhode Island; Boise City, Idaho; and Worcester, Massachusetts, are among the U.S. cities where homeowners looking to move would also face monthly mortgage payments that have more than doubled. In many cities where monthly payments would double under current rates, existing mortgage holders enjoy rates lower than 4%.
The lock-in effect is weakest in cities where home prices are lower and existing homeowners hold mortgages with relatively higher rates. Pittsburgh leads the pack with the smallest percentage increase in monthly mortgage payments across the 100 largest U.S. metro areas. “More affordable markets offer homeowners a smaller payment jump, not an escape from higher costs,” Realtor.com senior economist Hannah Jones observed in the report.
In Pittsburgh, a current typical mortgage holder pays $1,005 a month with a 4.1% interest rate, compared with the $1,441 a new homebuyer would be expected to pay. That’s still a 43% increase in what homebuyers would need to pay on a monthly basis, but in this real estate market, it passes for very good news. In Baltimore, Buffalo, New Orleans, Detroit, and Birmingham, Alabama, the percentage increase for a monthly mortgage payment also hovers under 60%, according to Realtor.com’s new data.
Jones believes the home affordability crisis will persist, even if mortgage rates shed a few percentage points. “Lower rates alone would not erase the affordability gap,” she said. “Slower home-price growth and rising incomes would also help narrow the difference between what households pay now and what it would take to buy.”
内容来自 Fast Company,版权归原作者所有。
阅读原文 ↗